Key takeaways
- On 9 October 2026 the ATO named the three rental deduction errors it sees most: loan interest, repairs vs capital works, and records.
- If you redraw or refinance for private spending, the interest on that part of the loan isn't deductible, even though it's the same loan.
- Fixing damage that existed when you bought the property, or replacing a whole kitchen or bathroom, isn't an immediate repair.
- You can only claim what you actually paid, backed by records. Double-counted property manager statements are a common trap.
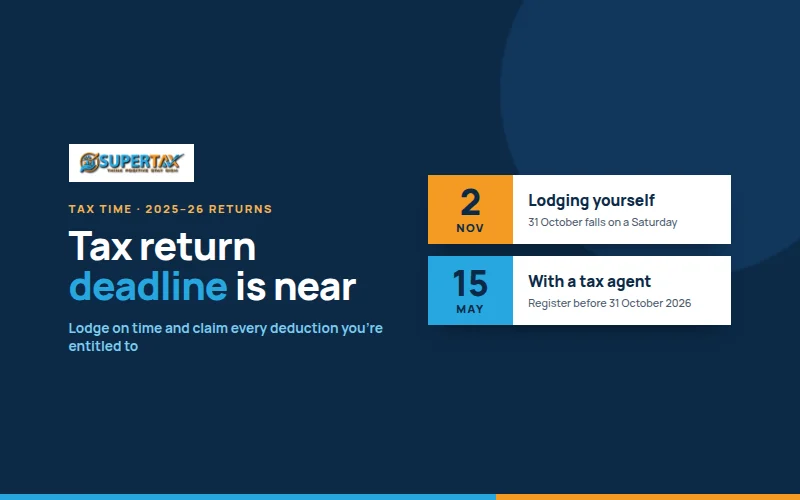
- Lodging yourself? The deadline is 2 November 2026. Register with a tax agent before 31 October for more time.
Rental property is one of the areas the ATO checks most closely, and with tax returns for 2025–26 due soon, it has just reminded tax professionals of the errors it keeps finding. If you own an investment property, these are the three things to get right before you lodge.
Why this matters now
The ATO receives rental data from banks, property managers, land titles offices and online platforms, and compares it with what owners claim. Errors can lead to amended assessments, penalties and interest. Getting it right the first time is far easier than fixing it later.
Mistake 1: claiming all the loan interest
Interest is deductible only on money borrowed to buy, or to earn income from, the rental property. If you redraw or refinance to pay for something private, such as a car, a holiday or school fees, the interest on that part is not deductible, even though it sits in the same loan.
Example: you have an $800,000 loan for a rental property, then redraw $50,000 to buy a car. Only the interest on the $800,000 is deductible. The interest on the $50,000 is private, and that split carries on for the life of the loan, including after any refinance.
Keep your loan statements, and keep investment and private borrowing in separate loans where you can.
Mistake 2: treating improvements as repairs
| Type of cost | How it's claimed |
|---|---|
| Repairs and maintenance that restore something to its original condition (fixing a leaking tap, repainting a damaged wall) | Deduct in full this year |
| Initial repairs to fix damage or defects that existed when you bought the property | Not deductible straight away; usually claimed over time as capital works |
| Improvements and renovations, such as a whole new kitchen or bathroom | Capital works, generally claimed at 2.5% a year |
| Appliances and fittings (dishwashers, heaters, blinds) costing $300 or less | Deduct in full this year |
| Appliances and fittings costing more than $300 | Depreciated over their effective life |
Also note: for residential properties bought after 9 May 2017, you generally can't claim depreciation on second-hand fittings that came with the property. A quantity surveyor's depreciation schedule shows exactly what you can claim.
Mistake 3: weak or doubled-up records
- Only claim amounts you actually paid. If an expense appears on both your property manager's statement and your own receipts, claim it once.
- Use your property manager's annual statement, not just the monthly ones, and check it against your bank records.
- If you own the property with someone else, claim income and expenses in line with your ownership share, usually 50/50 for joint owners.
- Keep records for at least five years, and for the whole time you own the property for capital gains purposes.
If you don't have a record, you generally can't claim it.
Other rental rules to check
- Declare all rental income, including bond money you kept, insurance payouts for lost rent, and fees from short-term platforms such as Airbnb.
- Holiday homes and part-year rentals: only claim expenses for the times the property was genuinely rented or available for rent at market rates.
- Travel to inspect or maintain a residential rental property is generally not deductible for individual investors.
- Vacant land: holding costs for land with no rentable property are generally not deductible.
- Rented to family or friends below market rate: your deductions may be limited to the rent you receive.
Rental property checklist
- Get your property manager's annual statement for 2025–26.
- Check loan statements and separate any private redraws.
- Sort each expense into repairs, capital works or depreciating assets.
- Use a depreciation schedule for capital works and fittings.
- Remove anything double-counted, and split expenses by ownership share.
- Declare all rental income, including short-term lets.
- Lodge by 2 November 2026, or register with a tax agent before 31 October.
Supertax prepares tax returns for property investors across Werribee and Melbourne's west. We'll check your interest, repairs and depreciation, and lodge under the tax agent program if you register before 31 October. See our property investor services, or book a free 15-minute consultation. Consultations are available in English, Punjabi (ਪੰਜਾਬੀ), Hindi (हिंदी), Urdu (اردو) and Gujarati (ગુજરાતી).
This article contains general information only and does not take your personal circumstances into account. Rental property rules can be complex, so speak with a registered tax agent before acting.
Own a rental property?
Talk to a registered tax agent at Supertax before you lodge.